Over the past six months, Axon’s shares (currently trading at $459.50) have posted a disappointing 9.4% loss, well below the S&P 500’s 18% gain. This may have investors wondering how to approach the situation.
Following the drawdown, is now a good time to buy AXON? Find out in our full research report, it’s free.
Why Are We Positive on Axon?
Providing body cameras and tasers for first responders, AXON (NASDAQ: AXON) develops technology solutions and weapons products for military, law enforcement, and civilians.
1. ARR Surges as Recurring Revenue Flows In
In addition to reported revenue, ARR (annual recurring revenue) is a useful data point for analyzing Law Enforcement Suppliers companies. This metric shows how much Axon expects to collect from its existing customer base in the next 12 months, giving visibility into its future revenue streams.
Axon’s ARR punched in at $1.64 billion in the latest quarter, and over the last two years, its year-on-year growth averaged 36.9%. This performance was fantastic and shows that customers are willing to take multi-year bets on the company’s product offerings. Its growth also makes Axon a more predictable business, a tailwind for its valuation as investors typically prefer businesses with recurring revenue. 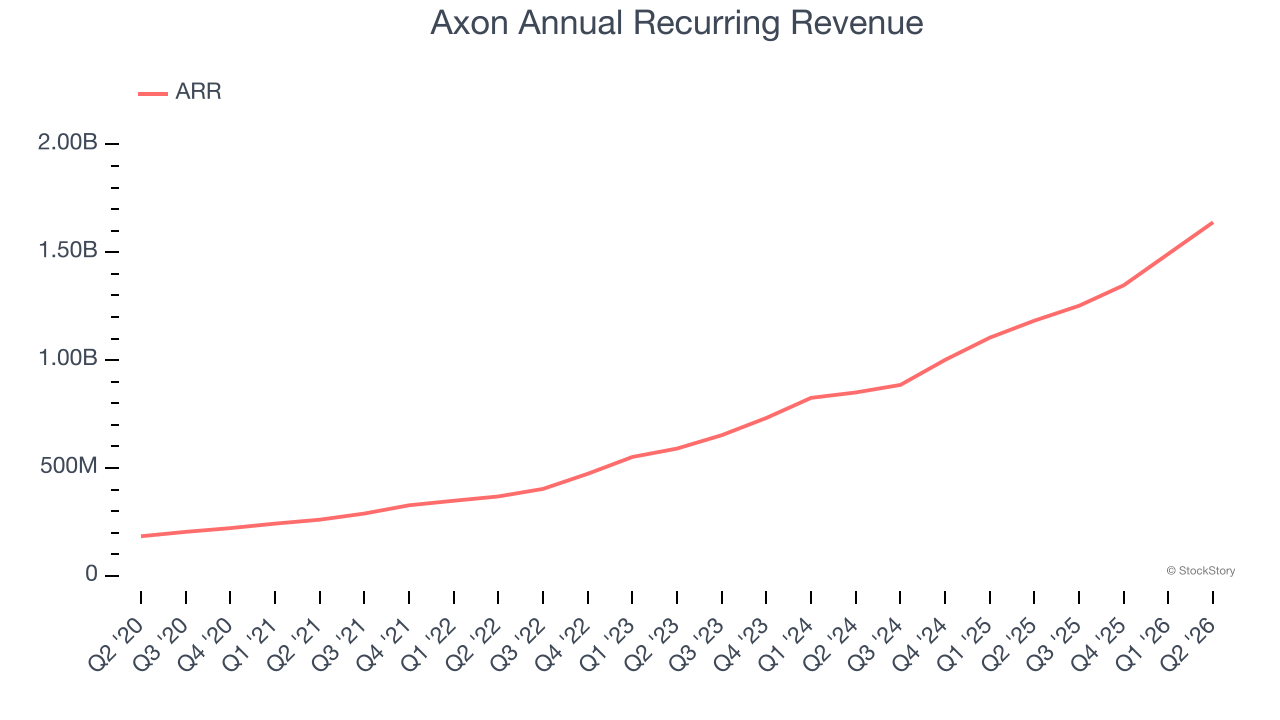
2. Projected Revenue Growth Is Remarkable
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite, though some deceleration is natural as businesses become larger.
Over the next 12 months, sell-side analysts expect Axon’s revenue to rise by 32.1%, close to its 31.9% annualized growth for the past five years. This projection is eye-popping and implies the market sees success for its products and services.
3. Outstanding Long-Term EPS Growth
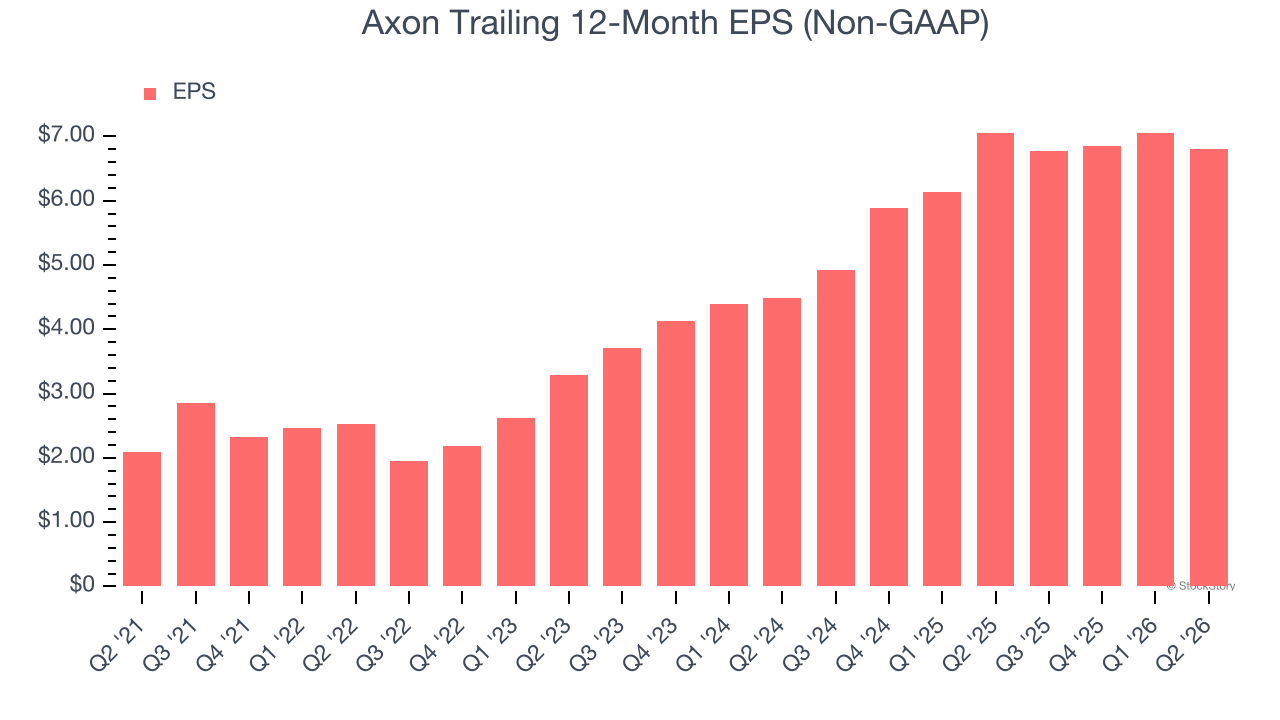
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Axon’s EPS grew at an astounding 26.6% compounded annual growth rate over the last five years. This performance was better than most industrials businesses.
Final Judgment
These are just a few reasons why we think Axon is a high-quality business. After the recent drawdown, the stock trades at 50.3× forward P/E (or $459.50 per share). Is now the right time to buy? See for yourself in our full research report, it’s free.
Stocks We Like Even More Than Axon
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.