Progressive trades at $225.20 and has moved in lockstep with the market. Its shares have returned 10.9% over the last six months while the S&P 500 has gained 7.5%.
Is PGR a buy right now? Find out in our full research report, it’s free.
Why are we positive on Progressive?
Starting as a small auto insurance company in 1937 with a pioneering focus on high-risk drivers, Progressive (NYSE: PGR) is a major auto, property, and commercial insurance provider that offers policies through independent agents, online platforms, and over the phone.
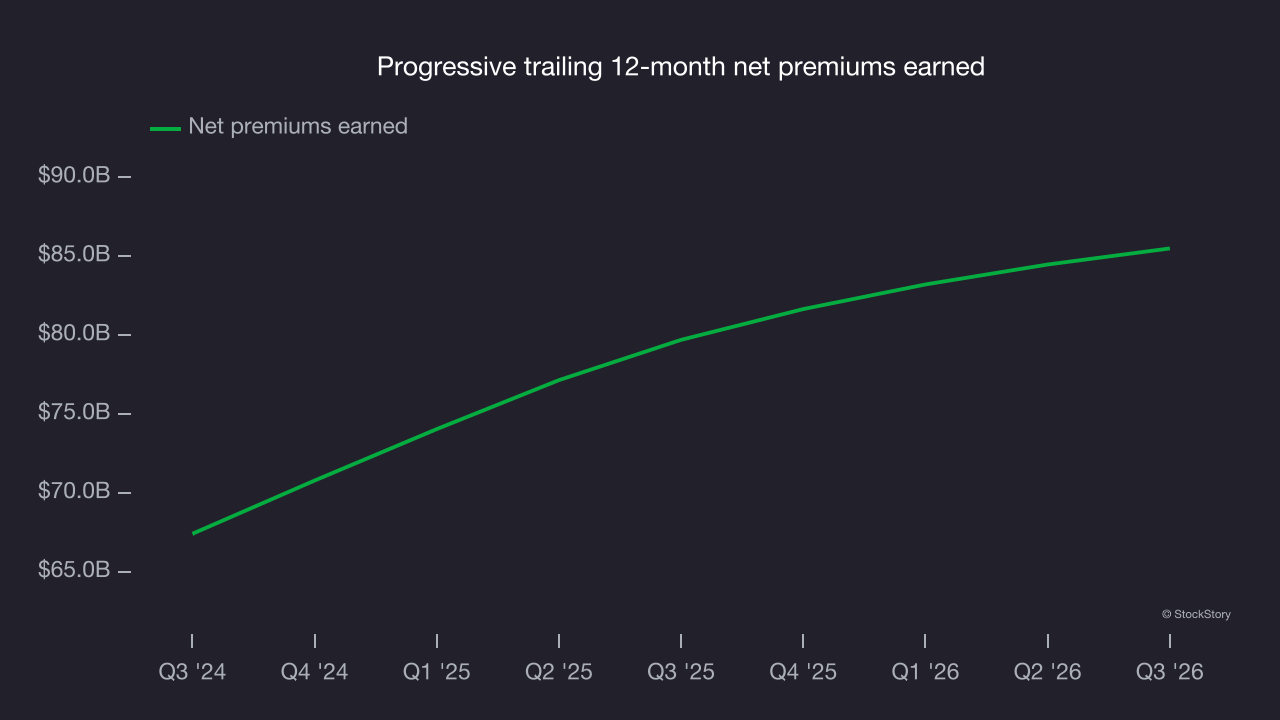
1. Net premiums earned skyrocket, fueling growth opportunities
When insurers sell policies, they protect themselves from extremely large losses or an outsized accumulation of losses with reinsurance (insurance for insurance companies). Net premiums earned are therefore net of what’s ceded to reinsurers as a risk mitigation and transfer strategy.
Progressive’s net premiums earned has grown at a 14.7% annualized rate over the last five years, better than the broader insurance industry and in line with its total revenue.
2. Outstanding long-term EPS growth
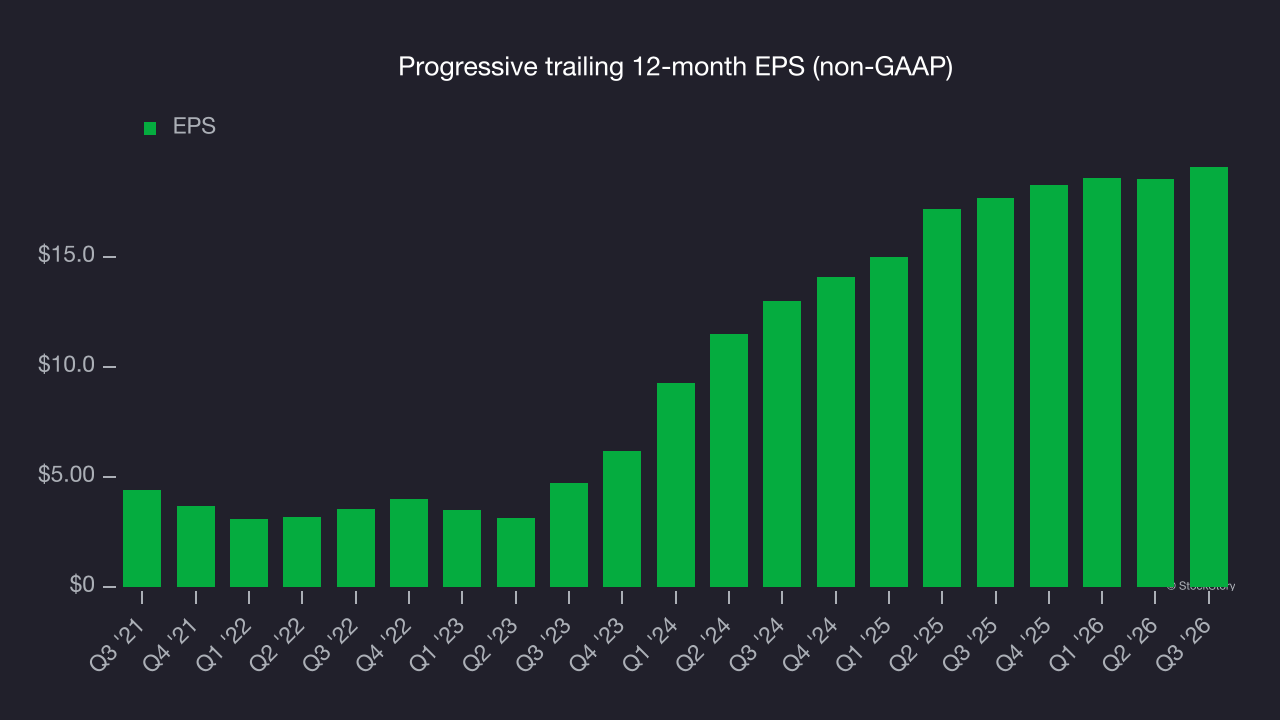
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Progressive’s EPS grew at 34% compounded annual growth rate over the last five years, higher than its 14.5% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
3. Stellar ROE showcases lucrative growth opportunities
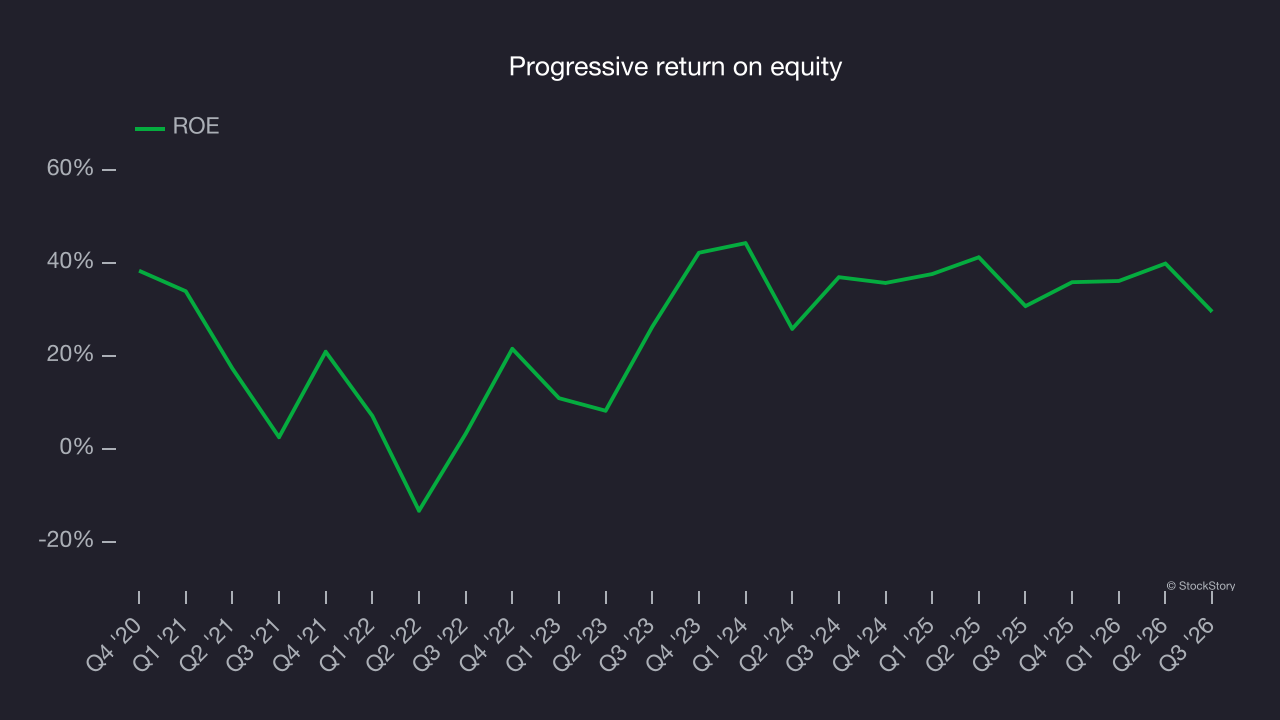
Return on Equity, or ROE, ties everything together and is a vital metric. It tells us how much profit the insurer generates for each dollar of shareholder equity entrusted to management. Over a long period, insurers with higher ROEs tend to compound shareholder wealth faster through retained earnings, buybacks, and dividends.
Over the last five years, Progressive has averaged an ROE of 26.1%, exceptional for a company operating in a sector where the average shakes out around 12.5% and those putting up 20%+ are greatly admired. This shows Progressive has a strong competitive moat.
Final judgment
These are just a few reasons Progressive is a high-quality business worth owning. At $225.20 per share (or 4× forward P/B), is now the time to initiate a position? See for yourself in our in-depth research report, it’s free.
Stocks we like even more than Progressive
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.